Protect what matters.
Understand how.
Life insurance should start with a better question, not a sales pitch. Learn the basics, think through your options, and ask for help only when you want it.
01 / THE IDEA
PROTECTION IS A FORM OF CLARITY
A plan isn't there to make life predictable. It's there to make the uncertain less disruptive.
At THE ASSET DEFENDER, we believe good financial decisions come from structure, not pressure. Life insurance is one part of that structure: a way to help protect the people who count on you. We'll help you understand the moving pieces before anyone asks you to choose.
A SIMPLER WAY FORWARD
Three steps.
One at a time.
01
Get oriented
Understand what term and whole life are built to do—and what they aren't.
02
Find your starting range
Use a straightforward worksheet to frame a conversation, not a final recommendation.
03
Ask for exactly what you need
Keep learning, ask the AI guide a general question, or reach a licensed human when you're ready.
Life insurance, without the runaround
Real quotes from top‑rated carriers. No sales call.
Compare term and whole life prices side by side, choose what fits, and apply online. A licensed agent is a text away if you want one, but never required.
- Top-rated carriers
- No phone call required
- Free to use
How it works
Three steps. All on your phone.
Share the basics
Name, contact info and state. About 30 seconds.
Compare live quotes
Real prices from top-rated carriers, side by side.
Apply online
Finish the carrier's secure application yourself, or text us for a second look first.
Need a medical exam? Many applicants don't. If your carrier requires one, the exam company schedules it with you, often at home or work.
Term vs. whole
Two options. Different jobs.
Term life
Most popular · lowest cost
Coverage for 10 to 40 years at a locked price. Built for needs with an end date: a mortgage, raising kids, replacing your income.
Whole life
Lifelong · guaranteed
Coverage that never expires, with level premiums and guaranteed cash value. Costs more; built for needs that never go away.
The tool also quotes return of premium, long-term care, accidental death and more. The free field guide explains each one.
Price matters. Strength matters more.
A policy may need to pay out decades from now. Every insurer below is rated A− or better by AM Best. Check any of them free at ambest.com.
- Banner Life
- William Penn
- Protective
- Principal
- Pacific Life
- Corebridge Financial
- John Hancock
- SBLI
- Prudential
- MassMutual
- Transamerica
- Assurity
- North American
- Nationwide
- National Life Group
AM Best ratings as of October 2026; ratings can change. Names belong to their owners; no endorsement implied.
Two ways to protect.
Different jobs to do.
01 / A DEFINED CHAPTER
Term life
Coverage for a set number of years. Often a practical starting point when the big need has an end date—children growing up, a mortgage getting paid down, or income that others rely on.
- Selected term, often 10, 20 or 30 years
- Generally no cash value
- Often lower initial cost for comparable coverage
02 / A LONGER HORIZON
Whole life
Designed for lifelong protection while required premiums are paid, with a cash-value component under policy terms. It usually means a higher premium commitment.
- Permanent design, subject to policy terms
- Cash value may build under the contract
- Requires careful review of guarantees and costs
This is a general comparison, not a recommendation. Features and costs depend on the actual policy and insurer.
If something happened to you tomorrow, would your family be financially prepared?
Your income may stop, but the mortgage, monthly bills, and everyday expenses won't. See how much life insurance your family might need to maintain their lifestyle, cover financial obligations, and protect the future you're building for them.
i No rate quotes, no application, and no data sent to us. Your numbers stay in this browser.
Debts + (income support × years) + other needs − available resources. A directional exercise only; it does not account for inflation, taxes or future changes.
Have a question?
Start there.
Our AI guide can explain general life-insurance ideas in everyday language. It doesn't quote rates, recommend a specific policy, or replace a licensed agent.
Not sure where to start?
Three taps.
Then your quotes.
Our AI guide asks your state, coverage and term, then carries your answers straight into your quote. Got a question first? It answers that too, in plain English.
- Never asks for your SSN, health or payment info
- No phone call, no obligation
Rather talk to a person? Text (512) 737-0176.
Tap an answer
General information only, not a recommendation. Please don't share medical, payment or ID details in chat.
Your agents
Real people behind every quote.
The Asset Defender is backed by Retirement Wealth Professionals, a Texas-based firm. Want a second look before you apply? Text us. It's free.
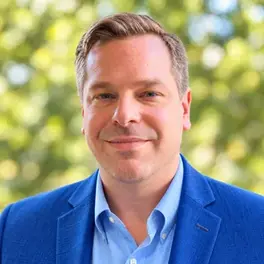
Derek Barmore
Co-founder · Licensed life & annuity agent
NPN 15648815 · AL, AZ, CO, FL, LA, MI, MN, OH, SC, TX, VA, WA
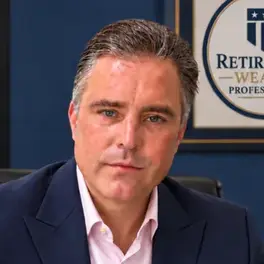
Cody Crawford, RICP®
CEO & Advisor · Licensed life & annuity agent
NPN 15364089 · All states except GA (renewal in progress)
Do I have to talk to anyone?
No. Quote and apply online. Text an agent only if you want to. If your carrier needs an exam, the exam company schedules it with you directly.
What does it cost to use?
Nothing. Carriers set the premium, and working with us doesn't add to it.
Are these real prices?
Yes, live quotes from the carriers. Your final rate is set after the carrier's underwriting.
Can I qualify with a health condition?
Often, depending on the carrier. Compare options, and share medical details only in the carrier's secure application.
Are you an insurance company?
No. We're licensed agents with Retirement Wealth Professionals. Your policy is issued by the carrier you choose.
Ready when you are.
Live quotes in about a minute. No call, no obligation.
THE ASSET DEFENDER
FIELD GUIDE 01
A clearer way
to protect
what matters.
A field guide for
the questions ahead.
Our free, plain-English guide walks through coverage needs, term versus whole life, questions for an agent, and the details worth understanding before you apply.
PDF · Read in about 12 minutes · No obligation
Answers without the fine-print voice.
The questions people actually ask, answered directly.
Do I need a phone call to get started?
No. Read, use the worksheet, or ask the AI guide a general question. If you want personal recommendations or real carrier options, request a licensed professional. You choose whether to have a conversation.
How much does term life cost?
It depends on age, health, coverage amount, term, state, carrier and underwriting. We will not invent a rate or promise approval. An agent can help with actual available options.
Is whole life better than term?
They solve different jobs. Term is typically used for a defined period and often costs less initially for comparable coverage. Whole life is designed for permanent coverage and includes cash value under its policy terms, usually at a higher initial cost.
Can I get coverage with a health condition?
Possibly, but it depends on the insurer and underwriting. Do not put medical details in this chat. A licensed agent can discuss what information a carrier needs through secure channels.
Are you an insurance company?
No. THE ASSET DEFENDER is an educational experience presented by Retirement Wealth Professionals. Insurance is issued by a carrier, subject to its terms and approval.
What happens after I download the guide?
You receive the PDF right away. You can receive educational email according to the form consent. Text messages are only an option if you check the separate SMS box. You can unsubscribe or reply STOP at any time.
This content is general education, not individualized financial, tax, legal, or insurance advice. No rates or eligibility are guaranteed. Policy features vary by insurer and state; a licensed agent and the carrier's contract provide the actual details. Insurance guarantees depend on the issuing insurer's claims-paying ability.
Clearer decisions for the people and possibilities you care about. An educational experience presented by Retirement Wealth Professionals.
The practical details
© 2026 The Asset Defender · Presented by Retirement Wealth Professionals
General education only. Not an insurance carrier or an offer of coverage.
The Asset DefenderPeople. Purpose. Protected.
Clearer life insurance decisions for the people you care about. Presented by Retirement Wealth Professionals.
The details
Reach a person
- (512) 737-0176
- [email protected]
- 8900 Red Bluff Rd
Pasadena, TX 77507
Insurance products are offered through Derek Barmore (NPN 15648815) and Cody Crawford (NPN 15364089), licensed life insurance agents in the following states: Derek Barmore in AL, AZ, CO, FL, LA, MI, MN, OH, SC, TX, VA and WA; Cody Crawford in all states except Georgia (renewal in progress). The Asset Defender is an educational experience presented by Retirement Wealth Professionals and is not an insurance company. Coverage is issued by the insurance carrier and is subject to underwriting and carrier approval. Quotes are estimates and not offers of coverage. Guarantees are based on the claims-paying ability of the issuing insurer.
The AI guide on this site provides general educational information only. It does not recommend products, sell insurance, or provide individualized insurance, tax, legal or investment advice. Insurance services are separate from any investment advisory services.
© 2026 The Asset Defender · Retirement Wealth Professionals